Volume-Tiered Occupational Accident Pricing and What Triggers Each Rate Bracket for Contractor Fleets
Fleet size, authority age, and loss history determine your occupational accident insurance rate.
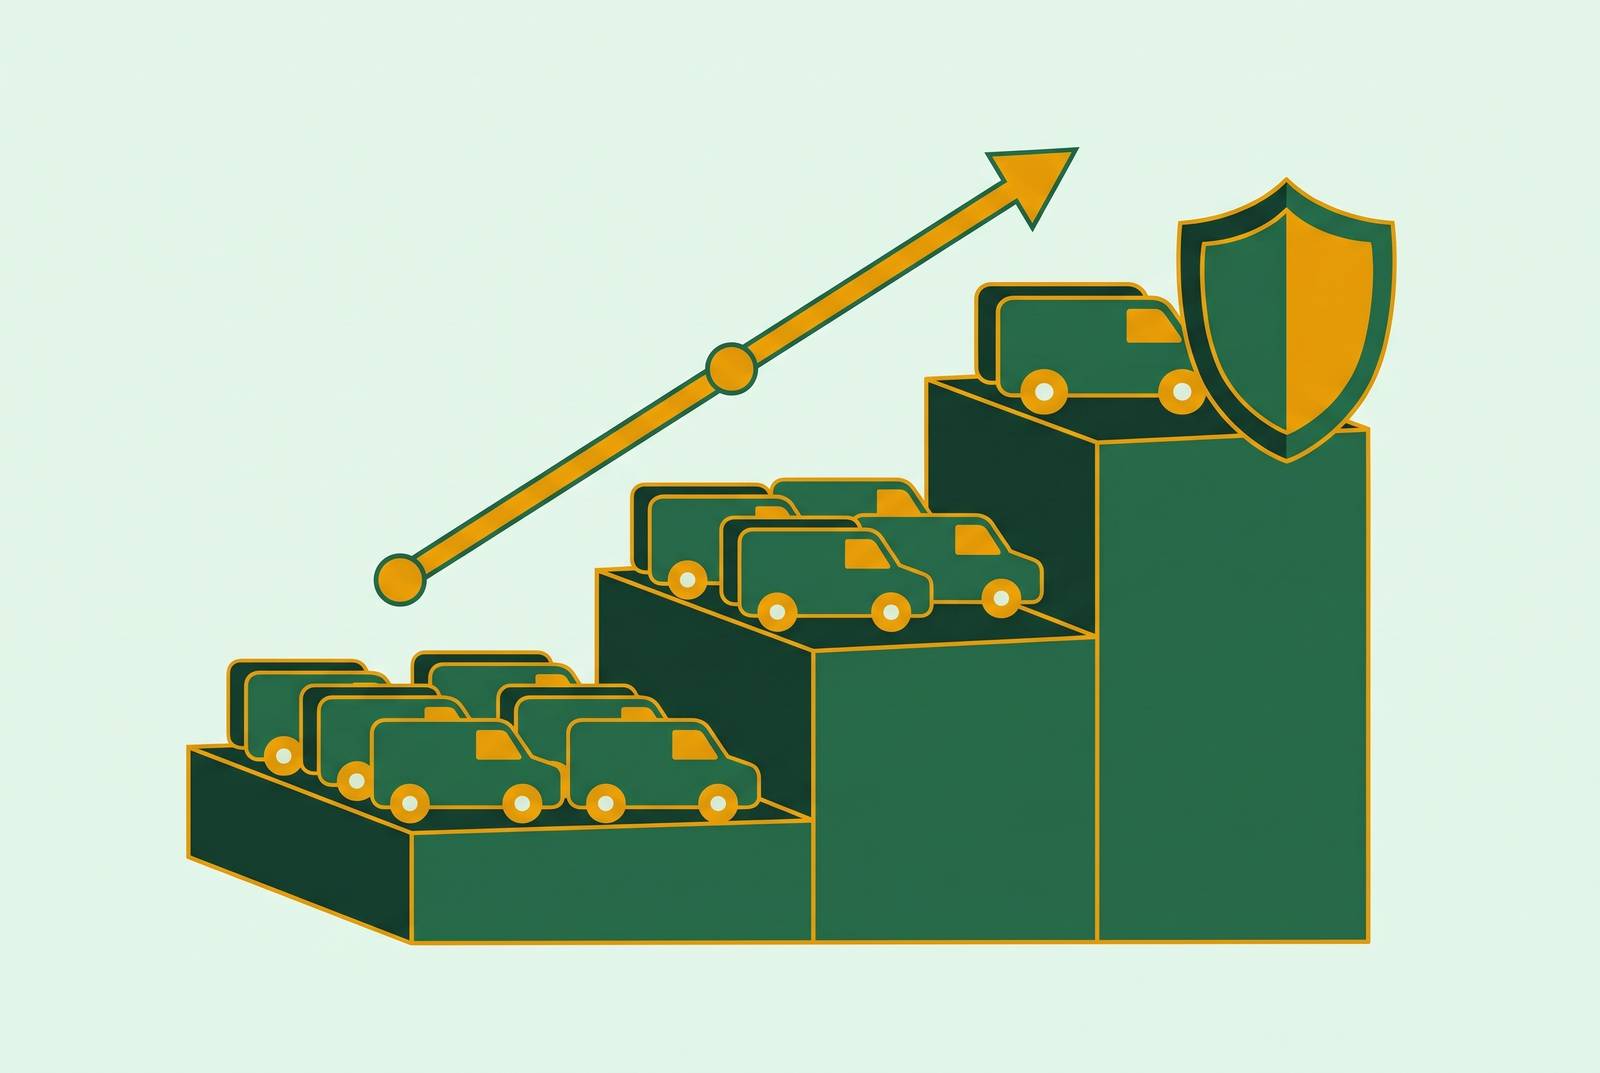
The price of bulk occupational accident insurance for independent contractor fleets depends on risk as well as volume. A fleet program can lower per-unit costs and consolidate coverage documentation, but headcount, operating authority age, loss history, work exposure, and benefit limits determine the effective rate.
Why occupational accident insurance exists as a separate product for 1099 contractor fleets
Independent contractors are excluded from workers’ compensation in most states by default. That leaves a gap for work-related injuries. Occupational accident insurance, or OAI, fills that gap by paying scheduled benefits after a covered accident, up to the plan’s limits. For fleets using 1099 contractors, it is a distinct coverage decision rather than a simple addition to commercial auto insurance.
The distinction rests on how benefits are defined. Workers’ compensation benefits are governed by statute, while OAI benefits come from the policy schedule. That schedule sets the accident medical, disability income, and accidental death and dismemberment benefits available to an injured contractor. As a result, two fleets buying OAI may be buying different levels of protection even before their size or operating history enters the calculation. A comparison of premiums without a comparison of schedules starts with the wrong denominator.
What the OAI benefit structure looks like before fleet size enters the equation
Accident medical limits, disability income, and accidental death and dismemberment, or AD&D, form the core benefit structure. Medical coverage has a per-accident maximum, which can be a modest entry-level cap or a multimillion-dollar limit depending on the tier chosen. Disability income pays a weekly benefit after a waiting period, with a limit on how long payments last. It also typically cannot exceed a defined share of pre-injury average weekly earnings. Each choice changes what the premium buys.
Under a plan with a 7-day disability waiting period, days 1–7 are not paid. Choosing a shorter or longer waiting period is therefore a cost lever, but it also changes when income protection begins. Weekly benefit levels and medical limits also change both the price and how much protection the plan gives. A cheaper schedule is not evidence of better volume pricing.
OOIDA’s Comprehensive tier costs $162.85/month and has higher medical, disability, and AD&D limits than its lower-priced tiers. That single-operator benchmark illustrates the effect of benefit selection. Coverage boundaries also shape the comparison. OAI covers sudden accidental injuries rather than occupational diseases or conditions that develop over time. A herniated disc from a single slip can fall within accident coverage, while chronic back pain from years of driving may not, so medical limits alone do not describe the protection being purchased.
How can contractor fleets get lower group rates as headcount grows?
Small fleets of 2–5 trucks begin to qualify for mini-fleet pricing, where the cost per unit starts to fall. The larger shift, however, is in the evidence underwriters use. At small fleet sizes, class averages provide the main basis for pricing because the fleet’s own record has limited statistical weight. As the contractor pool grows, its loss experience becomes more credible.
A larger fleet with a clean record can earn below-class pricing as the insurer gives more weight to its own claims history. A larger fleet with poor losses can experience the reverse. Crossing a headcount threshold may place it in a nominally cheaper volume bracket while producing a higher effective rate because its claims now exert more influence.
For a large fleet, the practical question is therefore not simply which headcount earns a discount. It is how the insurer weighs that contractor pool’s losses against class averages, with the benefit schedule held comparable. The available benchmarks do not establish a universal headcount-based price break or a single credibility threshold for all programs.
Why operating authority age is as significant a bracket trigger as fleet size
New operating authority is a separate risk classification. Underwriters can apply a new-authority surcharge on top of the rate associated with fleet size, so a growing contractor pool does not by itself remove the cost of being a new operator. Headcount and authority age work on different axes. One describes the scale of the exposure, while the other reflects the operating history available for assessment.
AtoB’s 2026 data provides a broad benchmark, placing new-authority surcharges at 25% or more on baseline premiums across insurance lines, including OAI, and describing meaningful rate reductions after three years of clean operation. Its significance is the existence of an authority-age pricing tier large enough to affect the value of volume savings. The passage of time helps only when the operating record supports the move.
A company adding contractors rapidly during its first year can therefore occupy a lower headcount-based bracket and a high authority-age bracket at the same time. The combined price may erase the expected volume benefit. Conversely, an established fleet with clean operation can approach renewal with both a more credible loss record and a more favorable authority-age position. Those are distinct reasons for a different rate, even when they arrive together.
How the risk class of the operation — commodity, haul type, and geography — sets the bracket floor
The work itself establishes the base risk class. Fleet size and authority age then affect the price from that starting point, while the underlying exposure remains. Commodity, haul type, and geography all enter this classification. A large, established fleet is still priced for the injuries its contractors are exposed to while doing the job.
For last-mile fleets, stop frequency is a central distinction. Local pickup and delivery gives contractors repeated chances to slip, trip, or get hurt while loading and unloading. Hotshot operations add exposure from frequent load cycles, ramps, and tight delivery sites. These patterns differ from over-the-road dry-van work, even when the vehicles belong to fleets with similar headcounts. The relevant unit of exposure is not merely a vehicle on a list.
In flatbed and step-deck operations, load securement and tarping can cause more severe injuries than in dry-van operations, while hazardous-material hauling is in a higher risk class. Geography can raise the starting point further. A last-mile fleet in a high-tier state can begin above an over-the-road dry-van fleet of the same size and authority age because their work exposures differ. Volume pricing can reduce cost within that classification, but it cannot reclassify the work by arithmetic.
What actually moves a fleet from one rate bracket to a lower one at renewal
The lesson for operators is to manage renewal around the factors that can change, rather than treating contractor count as the only lever. Loss history becomes especially valuable as a fleet grows beyond the point where its own experience has statistical credibility.
Fleets approaching three years of clean operation should proactively re-quote and request reassessment of the new-authority surcharge. The anniversary is known in advance. Although underwriters apply the age-related adjustment, operators should not assume that the existing price will automatically reflect their changed position. A renewal discussion can distinguish savings from a maturing authority from savings attributable to greater volume.
Coverage choices offer another lever, but with a different effect. Adjusting waiting periods, weekly disability amounts, or per-accident medical limits can reduce cost within a bracket without moving the fleet into another one. That can help manage cash flow while the operation builds toward a volume or authority-age threshold. It also means less protection in the area being reduced. A lower invoice should not be confused with improved underwriting treatment.
Telematics adoption provides a concrete part of the renewal discussion because it belongs in the fleet’s underwriting profile, together with losses and credentialing. The case here is qualitative. Rapid contractor growth without clean losses, telematics adoption, and proper credentialing can invite scrutiny that offsets expected volume savings.
Why the rate environment makes bracket management more consequential than it was three years ago
Rising base rates across the commercial trucking insurance market increase the cost of an unfavorable bracket position. The same pricing disadvantage becomes more expensive when applied to a higher base. That gives authority-age reassessment, loss-history management, and a current telematics profile greater financial significance. The rate environment increases the price of failing to account for changes in the fleet.
A fleet appropriately bracketed two years ago may now be overpaying if its operating history has matured but its underwriting position has not been re-evaluated. That possibility is distinct from the broader market becoming more expensive. Both forces can operate at once, leaving a fleet with a higher bill even when it has earned more favorable treatment relative to its earlier risk profile. At renewal, the fleet needs to look separately at changes in the market’s base rates and its own place in the pricing framework.
The distinction also limits what operators should expect. Better bracket management can address the avoidable cost of being priced on an outdated authority age, loss record, or operating profile.
How compliance infrastructure affects OAI bracket eligibility and underwriter confidence at scale
Underwriters assess more than the number of contractors. A fleet that keeps checking qualifications, coverage requirements, and compliance status has a different risk profile from one that cannot show records of those checks. Onboarding records establish part of that case, but current exposure depends on who is actually working. Real-time compliance monitoring confirms that an active contractor meets credentialing and coverage standards at dispatch. That narrows the gap between the policy’s intended exposure and the operation being insured.
This is the operational counterpart to the telematics argument. Both make the underwriting discussion about the managed fleet. For last-mile operators expanding from dozens to hundreds of contractors, manual back-office processes can break down and leave documentation gaps visible at renewal. Scale then creates two effects at once. It gives the loss record more statistical weight while making consistent administration harder to demonstrate.
A fleet buying OAI for 1099 contractors risks reclassification if it cannot document that they are independent. If those workers should have been employees covered by workers’ compensation, their OAI coverage may be challenged. Maintaining the contractor relationship properly is therefore part of maintaining the basis on which the coverage was purchased. An OAI policy is not a substitute for a defensible contractor relationship.
Bulk purchasing through a fleet program brings pricing and documentation together. Compared with contractors sourcing coverage individually, it gives the fleet a lower per-unit cost and a single point of compliance documentation, itself an underwriting positive. For large delivery fleets, that combination is the practical value of group coverage. The strongest case for a favorable rate is that contractors’ exposure is documented, their coverage is coherent, and their operating record supports the price being sought.